As Bangkok prays for the rain to clear ahead of next week’s global finance meeting, the country faces a pivotal moment not just to impress international policymakers, but to confront the deep structural challenges holding back its regions beyond the capital.
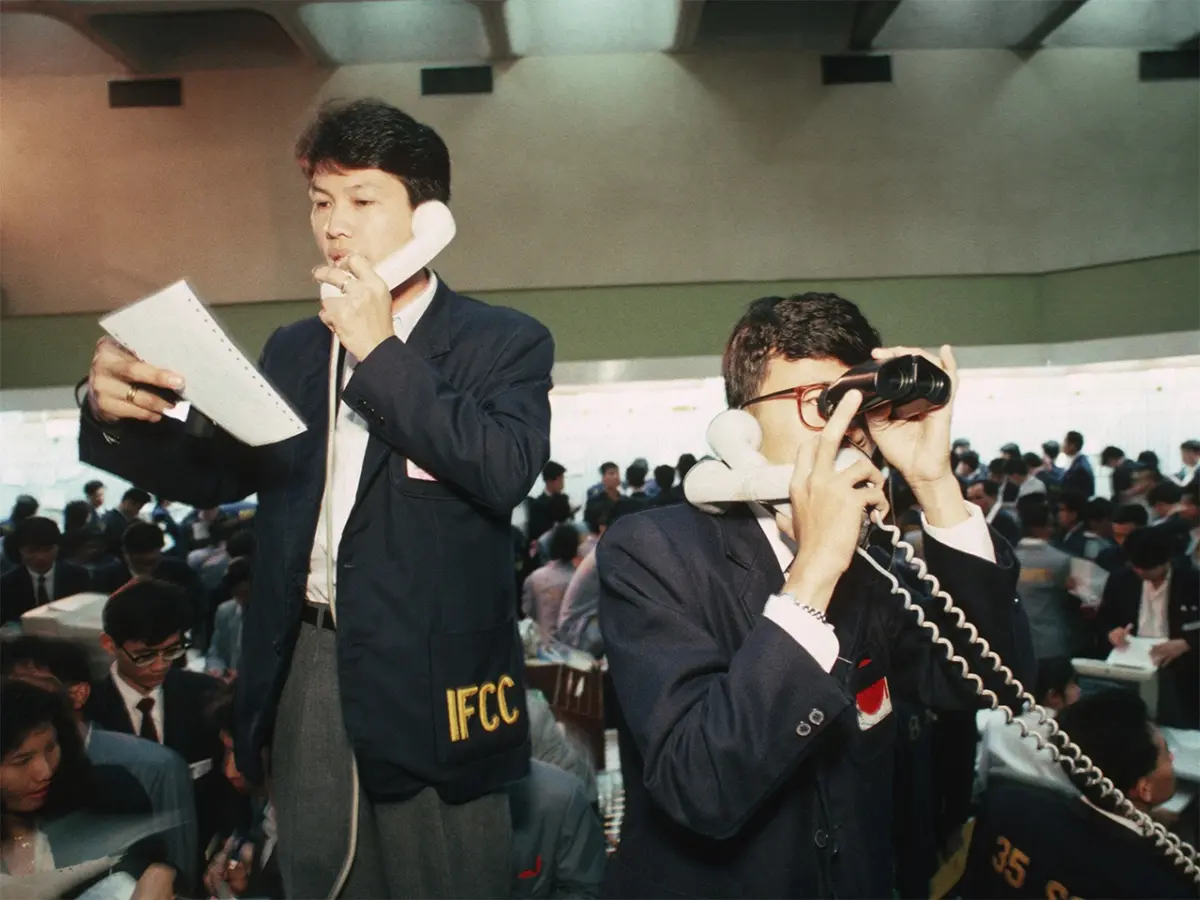
Lock up your datasets—Bangkok is playing host to one of the world’s largest gatherings of economists, central bankers, and finance ministers. The International Monetary Fund (IMF) and World Bank’s annual meeting, which leaves Washington every three years, will begin in the Thai capital on Monday for the first time since 1991.
Government officials here are calling this high-level conflab at the Queen Sirikit National Convention Center the “Olympics of Global Finance”. It is a high-profile title for more than 10,000 delegates in grey suits discussing interest rates, inflation, and sovereign debt. However, these global policymakers hold genuine influence, and Thai authorities are eager to make a lasting impression on the international stage.
Preparations across the capital have been intensive. Bangkok’s power lines have been pruned, workers have been given a day off to ease Friday traffic, and even the giant LED billboards are entirely on message. The logistical stakes have already proven high; a recent shortage of baggage handlers at the main international airport caused luggage to pile up, ultimately costing the CEO of Thai Airways his job. In preparation for the event, Prime Minister Anutin Charnvirakul and his cabinet are keeping a close eye on the weather, hoping for sunshine following the city’s recent bouts of flooding.
On the bright side, next week’s contingency plans are notably robust, with four distinct scenarios mapped out in case of flooding at the Queen Sirikit National Convention Center. If water levels reach 50 centimeters, the event will go on, but with a twist in the itinerary. Instead of being picked up from their hotel lobbies in electric-powered BMWs, VIP delegates will travel to the venue via the BTS Skytrain and underground metro. Arguably, the alternative commute would serve them well, as the elevated Skytrain remains one of the best ways to experience Bangkok and stands as a primary marker of the city’s massive transformation since the IMF and World Bank last visited in the early 1990s.
While these annual meetings are global in scope, they also provide a timely opportunity to take a closer look at the host country’s underlying economy. The World Bank’s latest report, released last month, paints an impressive picture of Thailand’s development over the past 35 years, highlighting its transition from an agrarian, lower middle-income country into one of the region’s most dynamic economies. It is a trajectory that is difficult to dispute, yet breaking into the World Bank’s top income bracket requires addressing the root causes of Thailand’s current upper-middle-income malaise.
At the current rate of growth, which crawls at a sluggish 2.2 percent, it will take Thailand another 30 years to become a high-income country. Achieving this milestone by 2037—the government’s stated goal—will require a radical overhaul of the economy and ambitious ideas that go far beyond building data centres and applying to join BRICS and the OECD. Annual economic growth would need to average five percent over the next 11 years, a figure that few observers in Thailand believe is achievable. The last time the country saw a recovery with those types of numbers was in 2012, following the previous year’s devastating floods, which drew global news coverage and dramatic headlines. Perhaps history will find a way to repeat itself.
One of Thailand’s primary structural problems is paradoxically also one of its greatest successes. Bangkok has firmly established itself as a top-20 global city, but this meteoric rise has come at the direct expense of other cities and provinces. The World Bank notes that Thailand suffers from “one of the world’s most extreme cases of urban concentration in its largest city.” The institution suggests the active development of second- and third-tier cities as a sensible remedy, with plenty of strong candidates waiting in the wings.
Chiang Mai, for instance, possesses the potential to transform from a regional hub into a vibrant creative capital. Meanwhile, Khon Kaen in the northeast boasts the universities and agricultural land necessary to become a natural center for agritech. While the private sector and tourism agencies are doing their part to promote these areas, there remains a distinct lack of urgency or financial buy-in from the central government.
Bangkok remains only one of two administrative areas in the country with a directly elected governor, while provincial leaders elsewhere are appointed civil servants. During the most recent general election in February, the reformist People’s Party campaigned heavily on decentralization. While the party swept the board in the capital, the nation’s heartlands—which arguably stand to benefit the most from regional empowerment in the long term—handed power back to the conservative status quo. Bangkok may have changed beyond all recognition since the 1990s, but Thai politics, come rain or shine, remains largely the same.
James Chambers is Monocle’s Asia editor.