It has been a whirlwind couple of weeks across the United States. The nation has moved at a rapid pace from the rigorous preparations surrounding the midterm elections to marveling at the political shifts overtaking Congress, all while keeping a watchful, anxious eye on the financial markets and the potential popping of any artificial intelligence bubble.
Yet, amid the constant stream of macro-political and technological noise, the American consumer still found time for a little retail therapy.
When the chief executive officers of a core group of prominent fashion and apparel brands weighed in with their latest quarterly financial results, conversations with financial analysts largely steered away from Washington politics and silicon valley algorithms. Instead, the dialogue zeroed in directly on the underlying forces shaping the current economic landscape—affordability, shifting consumer habits, and the overall macroeconomic outlook heading into the crucial holiday shopping season.
Market observers note that the current environment is creating a distinct divergence across the retail sector. "For the U.S., there’s clearly winners and losers, and you can see that in the performance," said Laurent Vasilescu, an analyst at BNP Paribas, discussing the recent trajectory of fashion brands. "It seems like the higher-end consumer seems to be still powering through. The U.S. still seems to be on the stronger side of things. Anecdotally, people would point to the credit card companies like Amex reporting good numbers."
Faced with these shifting dynamics, fashion chief executives are increasingly focusing on the operational levers within their direct control, rather than fretting excessively over unpredictable global headwinds.
"Regardless of the macro, we’re running our play," Ralph Lauren Corp. Chief Executive Officer Patrice Louvet told analysts during a recent earnings call. "We’ve got an eye on the long term because we want to make sure we’re continuing to build this brand in the right way for long-term success. Because we have both the diversity of growth drivers and the flexibility to pivot and take advantage of clear opportunities for Ralph Lauren in the marketplace, that’s where our confidence comes moving forward."
Louvet’s comments accompanied another "beat and raise" second quarter for Ralph Lauren, which reported a 9 percent increase in sales to reach $2.2 billion. Even so, the broader market showed transient signs of caution, as fresh concerns regarding the business climate in Europe briefly spooked some investors.
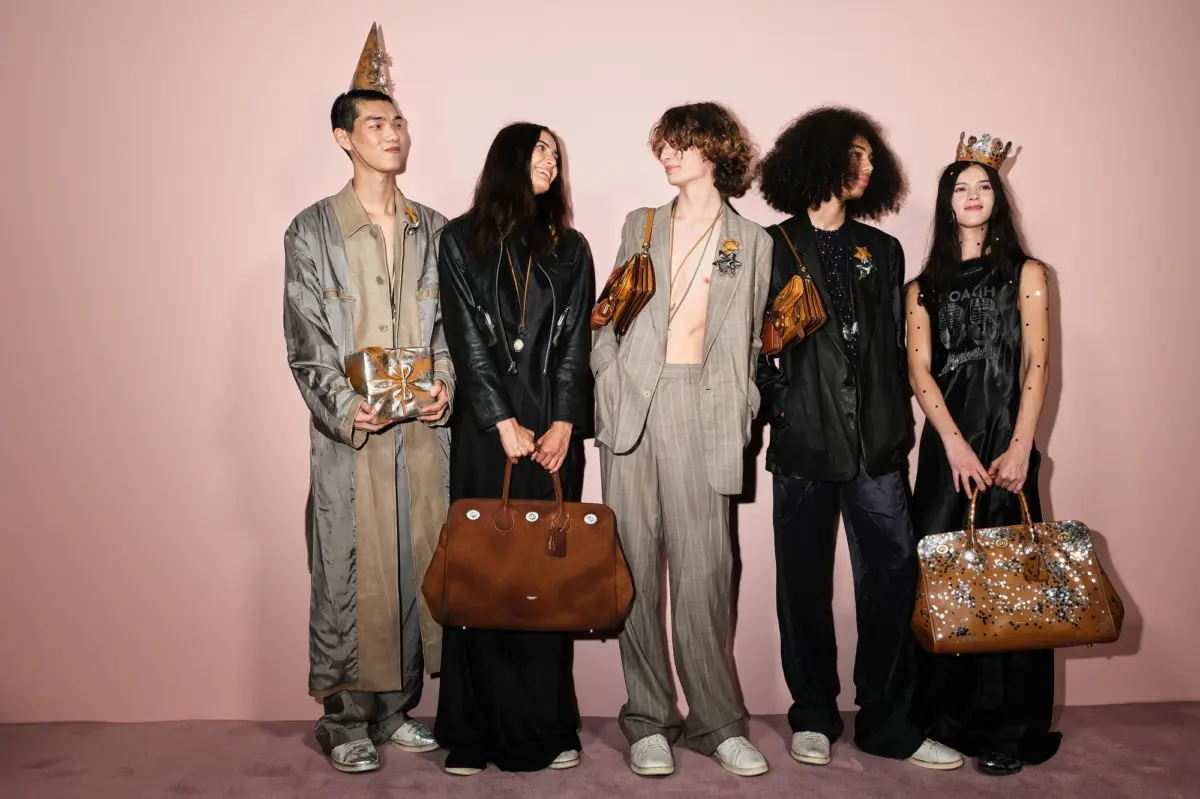
A similar sentiment of steady operational confidence echoed out of Coach parent Tapestry Inc. During the company’s fiscal first quarter, sales rose 12 percent to hit $1.9 billion, driven by robust brand health and targeted consumer engagement.
"In the U.S., while we see a discerning consumer, they’re choosing our category and our brand, and our value proposition has never been stronger," said Joanne Crevoiserat, CEO of Tapestry. Looking ahead, she noted that broader industry projections are anticipating midsingle-digit growth for the U.S. holiday season. "There’s a constructive backdrop overall as we head to holiday. At Coach, we’re looking at midsingle-digit growth expectations for both the quarter and for the year in North America. We’re ready to compete and win."
Both Ralph Lauren and Tapestry have spent more than a decade systematically proving their ability to compete and win. By ruthlessly cleaning up messy wholesale distribution channels, elevating their brand positioning through elevated design and marketing, and funneling substantial capital into storytelling, each company has successfully pushed its stock market valuation past the $20 billion threshold.
As these industry leaders forge a clear path forward, the pressing question across the sector is whether other legacy apparel and luxury players can successfully replicate their strategies. Other major industry entities, such as Michael Kors parent Capri Holdings and athletic apparel maker Under Armour Inc., are currently attempting to navigate similar turnaround and elevation playbooks.
"We know there’s market share to be regained and taken," said John Idol, CEO of Capri Holdings, during a discussion with analysts. "The industry and, in particular, some of the other luxury European luxury brands, are having a bit of a struggle right now. And we actually think this is a super time for us to be able to resonate with consumers who are being a bit more choiceful. We can see that with some other brands around the world who are enjoying the fruits of that success."
Capri Holdings is currently working to engineer a commercial rebound. The company’s quarterly sales fell 5.5 percent to $809 million, leaving Wall Street analysts watching closely for signs of a turnaround. Meanwhile, Under Armour remains in the midst of a deep, multi-year corporate reset. The athletic brand saw its sales drop 7 percent to $1.2 billion during its most recent quarter.
"Our focus at Under Armour is to build a stronger brand through compelling products and more consistent execution," said Kevin Plank, founder and chief executive officer of Under Armour. "We remain focused on revenue quality and profitability, putting our resources behind innovative products, aspirational storytelling and elite execution while maintaining expense discipline."
Navigating these turnarounds while keeping retail pricing stable presents a complex challenge for the broader industry. Blake Anderson, an equity analyst at Jefferies, noted that "the million-dollar question" facing retail executives is whether fashion and footwear brands will possess the pricing power necessary to hold the line on prices over the long term.
"I think that companies have generally said that there will be some promotion and that they want to still maintain or grow market share, but they’re not going to reduce prices or discount just for the sake of growing," Anderson explained.
He pointed out that the retail sector has operated within a distinctly inflationary environment for apparel and footwear over the past year. Part of that pricing pressure has stemmed from increased costs driven by tariffs and the subsequent passing of those expenses along to consumers.
"The question is always going to be, How much pricing power do these brands have and is it sticky? Does it sustain?" Anderson added. "There’s a lot of question, does this continue into next year or do we see lower pricing as we have to lap the higher pricing from this year? It really will depend on the brand and the company and really the momentum they have and the investments they’re making."